Subscribe for Our Latest Resources
"*" indicates required fields
We have put together a summary from our recent Webinar covering PCG2021/4 and Wealth Structuring for Paediatric Dentists with the help of our presenters Alice Wu – Associate Director of MGI and Jaxon King – Managing Director of Scion Private Wealth.
PCG 2021/4 is a Practical Compliance Guideline issued by the Australian Taxation Office (ATO). It outlines how the ATO assesses the allocation of profits within professional firms, especially where income is distributed through structures like trusts, partnerships, or companies. It applies to individual professional practitioners (IPPs)—such as directors, partners, or shareholders—who derive income from professional services firms.
This guideline is relevant for:
The ATO has confirmed that PCG 2021/4 remains in effect for the 2025–2026 financial year. Staying within the green zone (low risk) is essential because it:
Before scoring your arrangement, you must pass two gateways:
Then, assess your arrangement using up to three risk factors:
Vinnie runs his dental practice through a company owned by the Wen Family Trust. He’s entitled to $400,000 in total income.
This setup scores 8, placing Vinnie in the amber zone (medium risk). Because his market salary is hard to benchmark, only two risk factors are assessed.
However, if Vinnie adjusts the distribution so that 60% of the income stays in his name, his score drops to 7, moving him into the green zone—a much safer position.
For any questions about this topic, please contact Alice Wu on (07) 3002 4800 or email awu@mgisq.com.au
How specialist dental professionals can structure their wealth and invest strategically to turn today’s business income into tomorrow’s financial freedom.
Running a successful dental practice – particularly in specialist areas like paediatric dentistry – comes with more than just high income. You face unique challenges: complex income structures, specialist equipment costs, staff obligations and potential litigation risks.
While compliance with PCG 2021/4 is essential for meeting tax obligations, it’s what you do with that income afterward that defines your long-term financial success. In this article, we explore the strategies discussed in our recent AAPD webinar, turning expert insights into practical advice to help you turn tax-smart profits into lasting personal wealth.
At Scion Private Wealth, we use a proven framework to guide our high-income clients:
1. Structure – Protect, Distribute & Grow
2. Strategy – Make Money Work Harder Than You Do
3. Succession – Plan Ahead for Life Beyond the Practice
Dentists need asset protection and tax efficiency. Here’s how different structures compare:
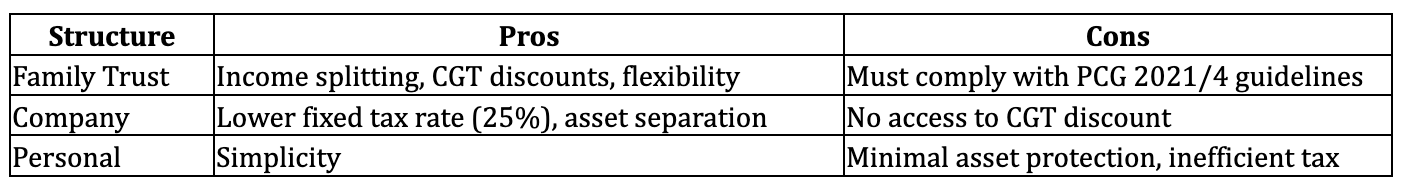
Best Practice: Use a combination – e.g., a company to operate the practice, a service trust for income splitting and a family trust to distribute profits tax-effectively.
The ATO’s guidelines around income allocation don’t eliminate trusts- they just raise the bar for consistency and evidence.
To stay in the green zone:
Case in Point: Dr Sarah, a paediatric dentist, restructured her trust for compliance while using excess profits to fund a family investment company for her children’s future.
Dentistry is a high-liability profession. Lawsuits, staff disputes, or even property leases can place personal wealth at risk.
Asset Protection Strategies:
When structured well, surplus profits can fund assets that pay you – even while you sleep.
Options to Consider:
Dr James invested $100K annually into global healthcare and infrastructure funds. Five years later, his portfolio now generates $32,000 in passive income annually.
Super can be a secret weapon for dentists- especially as high-income earners facing top marginal tax rates.
Key Tips:
Your personal wealth journey can also support the next generation.
Tax-Efficient Options for building intergenerational wealth:
Many dentists delay practice succession planning until it’s too late—or worse, sell without a strategy.
Exit Pathways:
Dr Helen gradually transitioned her practice to a junior dentist, retained the clinic’s building, and now earns $60K per year in rental income while mentoring part-time.
Your practice should support your life – not the other way around.
Use surplus income to:
“You’ve built a great practice. Now it’s time to build a great life.”
Too many high-income professionals leave wealth to chance. A strategic, tailored approach can mean the difference between a busy working life and a truly wealthy one.
Key Takeaways:
Let’s explore how your business success can fund your long-term lifestyle goals.
For any questions about this topic, please contact Jaxon King on (07) 3778 6800 or email jking@scionprivatewealth.com.au.
Scion Private Wealth is a trusted advisor of MGI.
The Australian Taxation Office (ATO) has shared the specific risks it will be monitoring for the 2024-2025 tax year. Following on from the small business focus areas identified in Quarter 4 of the this year and on the warnings it issued for the last financial year, there are a number of issues that remain firmly at the top of the list when it comes to tax compliance. As the 2025 end of tax year approaches, the ATO is sharpening its focus on several key areas to ensure compliance and integrity within the tax system. This year, the ATO is particularly vigilant about claims for rental property deductions, work-related expenses, cryptocurrency and undeclared income from the sharing economy. If you’re preparing for tax time, understanding and ensuring you’re fully compliant in these areas can help ensure you get your lodgment right the first time. Let’s take a look at the ATO focus areas for tax time 2025 in a bit more detail.
Investment properties were a firm focus at tax time in 2024 and the ATO continues to scrutinise rental property deductions closely, ensuring that claims are legitimate and accurately reflect expenses incurred. Recent audits from the tax office indicate that 90% of rental property owners are getting their tax returns wrong.
According to ATO Assistant Commissioner, Robert Thomson: “People aren’t apportioning correctly between interest relating to private use and the interest that relates to the income they’re generating from their investment property.”
Common areas where taxpayers might encounter issues include:
The ATO employs sophisticated data-matching techniques and collaborations with financial institutions to identify discrepancies and ensure compliance. Rental property owners should maintain detailed records and seek professional advice to ensure their claims are accurate and justifiable. A registered tax agent can help ensure your tax return is accurate.
As in the previous couple of years, work-related expenses are another area under the ATO’s microscope. Changes were made in 2023 to the fixed rate method of calculating a working from home deduction and taxpayers were required to keep more detailed documentation. However, as these rues have now been in place for a couple of years the expectation is that you must have comprehensive records to substantiate your claims.
“Copying and pasting your working from home claim from last year may be tempting, but this will likely mean we will be contacting you for a ‘please explain’. Your deductions will be disallowed if you’re not eligible or you don’t keep the right records.” Mr Thomson said.
To avoid issues, taxpayers should adhere to the following guidelines:
Accurate record-keeping and adherence to ATO guidelines are essential to ensure compliance and avoid audits or penalties.
Remember, there are 3 golden rules for claiming a deduction for any work-related expense:
The rise of the sharing economy has introduced new challenges for tax compliance. Platforms like Airbnb, Uber, and various freelancing sites have made it easier for individuals to earn income that may go undeclared.
The ATO is particularly focused on:
The ATO collaborates with sharing economy platforms to access data and identify undeclared income. These sophisticated data matching systems mean that if you decide to not report your income from these platforms then you are much more likely to trigger a review by the ATO. Participants in the sharing economy should maintain comprehensive records of their earnings and report them accurately to avoid penalties.
Cryptocurrency and crypto based business models are an emerging area of focus for the ATO. Australian tax payers have been warned that they need to report all cryptocurrency related capital gains, losses and income in their tax returns. The Australian Taxation Office treats cryptocurrency as property for tax purposes. This means that individuals and businesses are required to pay capital gains tax (CGT) on cryptocurrency transactions, depending on the profits they make.
When you sell a cryptocurrency asset you need to work out whether you made a capital gain (i.e. you made a profit) or a capital loss (i.e. you lost money) to determine how much capital gains tax (CGT) you’re required to pay. You need to report your gains and losses in your tax return and pay income tax on net gains.
It’s also important to understand whether you’d be considered an investor or a trader for tax purposes. If you buy and sell assets regularly, you may be considered a trader, which changes the taxation treatment of any gains or profits you make on your asset sales.
The advice is also to not rush to submit your tax return, particularly if you received income from multiple sources. “By lodging in early July, you are doubling your chances of having your tax return flagged as incorrect by the ATO.”
As the ATO intensifies its focus on rental property deductions, work-related expenses, cryptocurrency and undeclared income from the sharing economy, it is more important than ever for taxpayers to be diligent and compliant. By understanding the ATO focus areas and maintaining accurate records, taxpayers can navigate their obligations confidently and avoid the risk of audits and penalties. If in doubt, seeking professional advice from the tax experts at MGI can provide the necessary guidance to ensure compliance and peace of mind in the 2025 tax year.
Check out our recent blog on Personal Services Income (PSI) to ensure that you are categorising your business and services correctly.
For more information or personalised advice on your tax obligations, feel free to reach out to the experts at MGI South Qld. We’re here to help you navigate the complexities of the Australian tax system with ease and confidence.
You might also be interested in our most recent blog on the ATO small business focus areas for Q4 of the 2024/25 financial year.
The Australian Taxation Office (ATO) has recently released an updated set of small business benchmarks based on 2022-23 financial year data. The benchmarks are reviewed annually and broken down into 100 industries and they’re used by the ATO to assess whether a business might be under-reporting taxable income and over-claiming deductions.
The ATO provides Small Business Benchmarks as a tool to help businesses compare their financial performance against industry standards. These benchmarks are derived from data collected from tax returns and activity statements of businesses across various industries. They serve as a guide for businesses to assess their performance and ensure they are meeting their tax obligations.
The ATO uses these benchmarks to identify businesses that may be avoiding their tax obligations. By comparing a business’s financial ratios to industry standards, the ATO can detect anomalies that may indicate underreporting of income or overstatement of expenses. Businesses that fall significantly outside the benchmark ranges may attract scrutiny and potential audits.
However, they can also be a useful tool for any business to compare your performance, including turnover and expenses against others in your industry. You might be able to identify opportunities to make improvements to your business.
The benchmarks cover 100 industries and over 2 million small businesses around the country. The industries include:
What If Your Business Falls Outside the Industry Benchmarks?
You might find that your business falls outside of these benchmarks. If you’re above or below the standards for your industry it doesn’t necessarily mean you’ve done anything wrong however, it’s an indicator that it’s worth reviewing your business plan.
ATO Assistant Commissioner Tony Goding said: “While we never use the benchmarks in isolation, small businesses who fall outside the ATO’s benchmarks are more likely to trigger a closer examination from us to identify if they are making mistakes or deliberately doing the wrong thing.”
If your business’s expenses are higher than the industry average, it may suggest that your expenses are high relative to sales. This might show that your:
Such discrepancies can trigger ATO reviews or audits to ensure compliance.
Conversely, if your expenses are significantly lower than the industry average, it might indicate that:
While being below the benchmark isn’t inherently negative, it’s essential to ensure that all expenses and obligations are accurately reported.
Understanding where your business stands in relation to the ATO Small Business Benchmarks is crucial. Regularly comparing your financial ratios to industry standards can help identify areas for improvement and ensure compliance with tax obligations. It also aids in making informed business decisions and maintaining financial health.
At MGI South Qld, we specialise in business performance analysis and helping businesses navigate the complexities of tax compliance and financial performance. Our team can assist you in:
Contact us today to ensure your business aligns with industry benchmarks and maintains robust financial health.
Loans now available for disaster-affected businesses from the Western Queensland surface trough and associated rainfall and flooding.
Financial assistance is available for primary producers, small businesses and not-for-profits impacted by flooding in Western Queensland.
Disaster Assistance Loans and Essential Working Capital Loans have been activated for businesses in Barcoo, Boulia, Bulloo, Diamantina, Longreach, Murweh, Paroo, Quilpie, and Winton local government areas.
These loans are designed to support small businesses to re-establish operations relating to:
Eligible primary producers, small businesses and not-for-profits can apply for:
For more information on eligibility and how to apply – follow these links: Disaster Loans and Disaster Assistance (Essential Working Capital) Loans
Should you have any questions or wish to discuss this matter further, please do not hesitate to contact the team at MGI.
Every quarter the Australian Taxation Office (ATO) shares their areas of focus when it comes to small businesses meeting their tax and superannuation obligations. These insights help businesses remain compliant with tax obligations and avoid costly penalties. As we enter the final quarter of the 2024/25 financial year, the ATO has announced three key focus areas for small business owners to be aware of. These include undeclared contractor income, suggested changes in GST reporting frequency and compliance with small business boost measures. Staying informed and aligned with the ATO small business focus areas can help you avoid ATO scrutiny and maintain good standing with the tax office.
As part of the taxable payments reporting system (TPRS), businesses must report payments made to contractors for providing the following services.
If you work as a contractor and provide any of these services, the business you contract to will report those payments to the ATO on their TPAR and you need to include this income on your tax return. Contractors need to be aware that the ATO is using sophisticated data matching techniques to identify contractors reported through the TPRS. This quarter, the ATO will be increasing its scrutiny on contractors who:
To remain compliant, contractors should ensure all income is accurately declared in their small business tax returns. The ATO uses data-matching technology to detect discrepancies between reported income and what is actually received.
From March 2025, the ATO is encouraging more small businesses to transition from quarterly to monthly BAS (Business Activity Statement) reporting for GST purposes. If you have a history of failing to comply with your tax and GST obligations you may receive communication from the ATO notifying you of your new monthly reporting cycle effective from 1 April 2025. You are more likely to be migrated to the new reporting cycle if you have not responded to previous communications from the tax office and demonstrate a poor compliance history, for example:
The aim is to help businesses:
While not mandatory for all small businesses, monthly GST reporting is highly recommended for businesses that frequently receive GST refunds or are struggling with quarterly reporting accuracy. The ATO is focusing on educating and assisting businesses with this transition during Q4.
If you’re considering switching to monthly GST reporting, speak with your accountant or advisor to determine if it’s the right move for your business.
The ATO continues to monitor compliance with the recently introduced small business boost measures, which were designed to support digital adoption and skill development. These include:
The ATO is actively reviewing claims to ensure they meet eligibility requirements. Key risks include:
Among the main errors being reported for the Skills & Training Boost program include:
To remain compliant, ensure your claims are accurate, well-documented, and within the guidelines set out by the ATO.
The ATO will also continue to focus on non-commercial business losses, small business capital gains tax (CGT) concessions, business income is not personal income and GST registration and income of taxi, limousine and ride-sourcing services.
Staying compliant with ATO small business benchmarks and requirements doesn’t need to be overwhelming. By understanding the ATO’s focus areas and keeping your tax records and obligations in check, you can reduce risk and focus on growing your business.
At MGI South Qld, we help small businesses stay on top of their tax administration and compliance requirements. If you’re unsure about your income declarations, GST reporting obligations or small business boost claims, our team is here to support you.
Contact us today to stay ahead of ATO updates and ensure your business remains compliant for Q4 and beyond.
The general transfer balance cap is set to increase to $2 million on 1 July 2025, following the release of quarterly CPI data.
With all groups CPI figure reaching 139.4 for the December 2024 quarter, the general transfer balance cap will be indexed for the 2025–26 year, increasing to $2 million from $1.9 million.
The cap limits the amount of money that can be transferred into the retirement phase in super. The increase means clients commencing their first retirement phase income stream in 2025–26 will start with a personal transfer balance cap of $2 million.
Clients who already have a personal transfer balance cap that they have not fully utilised at any time in the past will see their cap increase on 1 July 2025 by a smaller amount due to proportional indexation.
This increase also affects other superannuation rules and concessions including the total superannuation balance, which will also increase to $2 million.
A member’s total super balance at 30 June 2025 will need to be less than $2 million for them to access the standard non-concessional contributions cap.
The 3-year bring forward rule will be limited against a higher Total Superannuation Balance as per below:
To 30 June 2025

From 1 July 2025

If you have any queries or concerns or need further advice and support about superannuation changes please don’t hesitate to reach out to the team at MGI.
Small businesses, primary producers and not-for-profits impacted by ex-Tropical Cyclone Alfred in South East Queensland can now apply for disaster assistance loans to support their recovery.
Tropical Cyclone Alfred – Exceptional Disaster Assistance Recovery Grants are available to assist directly impacted primary producers, small businesses and non profit organisations with the costs of clean-up and reinstatement.
Disaster recovery grants are now available to primary producers, small business and not-for-profits in 16 local government areas that were impacted by ex-Tropical Cyclone Alfred.
These grants will fund up to $25,000 for clean-up and return to operation costs, including:
For more information on these points below and to apply click here: Disaster Assistance Recovery Grants
Queensland Rural and Industry Development Authority has opened applications for:
Disaster Assistance Loans up to $250,000 and Essential Working Capital Loans up to $100,000 are available to eligible operators.
Loans can be used to repair damaged assets, restock supplies, and for the costs of sustaining operations and have been activated for eligible operators across the Local Government Areas of Brisbane, Bundaberg, Fraser Coast, Gold Coast, Gympie, Ipswich, Lockyer Valley, Logan, Moreton Bay, Noosa, Redland, Scenic Rim, Somerset, Southern Downs, Sunshine Coast, and Toowoomba.
Concessional loans are available provided that certain criteria are met. For further information regarding what assistance is available, loan amounts, terms, interest rates, eligibility and how to apply, visit the QRIDA website.
The links allow you to toggle for criteria for each industry e.g. Primary Producers, Small Business and Not-for-profit organisations.
Should you have any questions or wish to discuss this matter further, please do not hesitate to contact the team at MGI.
Not for profit entities that aren’t registered charities are now required to complete an annual Not For Profit Self Review return.
The NFP self-review return due date is approaching. For all NFP’s who have yet to lodge a return with a 30 June 2024 year end the new lodgement date is 31 March 2025.
Non-charitable NFPs with an active Australian business number (ABN) must lodge the return to confirm their eligibility for income tax exemption.
However, an entity that has a different year end date, will need to apply to the ATO to adopt a Substituted Accounting Period (SAP) and be approved.
SAPs may be granted to NFPs where they can demonstrate that an ongoing event, industry practice, business driver or other ongoing circumstance makes 30 June an inappropriate or impractical balance date.
For more information on lodgement due dates and substituted accounting periods please see link: ATO Lodgement Dates
Various categories of NFPs will not be included in the new return and will not have a lodgement obligation.
However, if your NFP falls into the below category it will need to self-assess and lodge a return with the ATO:
Any NFP’s who do not meet the above categories but are either one of the following are considered exempt from lodging the return:
The not-for-profit (NFP) self-review reporting is arguably the largest change in this sector since the establishment of the Australian Charities and Not-for-Profit Commission (ACNC) in late 2012. It is important to note that no changes have been made to the legislation allowing entities to self-assess their income tax exempt status. Every organisation that has been appropriately self-assessing its status the Income Tax Assessment Act 1997 will remain eligible to self-assess for the income tax exemption from 1 July 2024.
The new requirement asks these organisations to formally report the specific basis of their assessment, by reference to the category of organisation and the specific eligibility criteria that apply to that category.
It has always been a requirement that these organisations review their eligibility to self-assess for the income tax exemption on an ongoing basis and now it will be a requirement that this assessment is lodged with the Australian Taxation Office (ATO).
We note that there is no requirement to provide detailed financial information outside of disclosing a revenue band into which the organisation falls, which allows the population to be dissected on the basis of size in the future.
For those organisations already identified by the ATO, the return will be automatically generated. It will show on the entity’s ‘For action’ page in Online services for business (OSB), which may help identify the requirement for some organisations that lodge periodic activity statements via this method. Tax or BAS agents who assist with meeting GST obligations may be well-placed to identify.
Call to Action
As the Not For Profit self review return reporting regime is relatively new, we would suggest the following actions:
Should you have any questions or wish to discuss this matter further, please do not hesitate to contact our office.

Made in Queensland (MIQ) is a $121.5 million Queensland Government program helping small and medium sized manufacturers to increase international competitiveness, productivity and innovation, and to generate high-skilled jobs for the future. MIQ supports traditional manufacturers to adopt industry leading equipment, technologies, systems and processes.
Applicant guidelines for Made in Queensland round 7 are now available and the online application form is open. Applications will close at 1.00pm on Friday 24 January 2025.
Queensland-based manufacturers looking to adopt industry leading equipment, technologies, systems and processes that include energy efficiency, export, reshoring, supply chain improvements, sustainability and/or advancement of decarbonisation and net zero outcomes are encouraged to apply for matched funding grants of $50,000 to $2.5 million.
In Round 7, up to $2.5 million (excluding GST) of available funding has been set aside for applications which do not involve the purchase of equipment (see Section 2.3.3) and are seeking less than $250,000 (excluding GST) each in funding. These applications will proceed through the same two-stage competitive selection process as all other applications
Successful MIQ applicants will be required to execute a funding agreement with the Queensland Government. An example funding agreement is provided below for information purposes.
MIQ – Round 7 Funding eligibility and application guidelines
Please contact the team at MGI if you have any questions or need assistance in your application.